
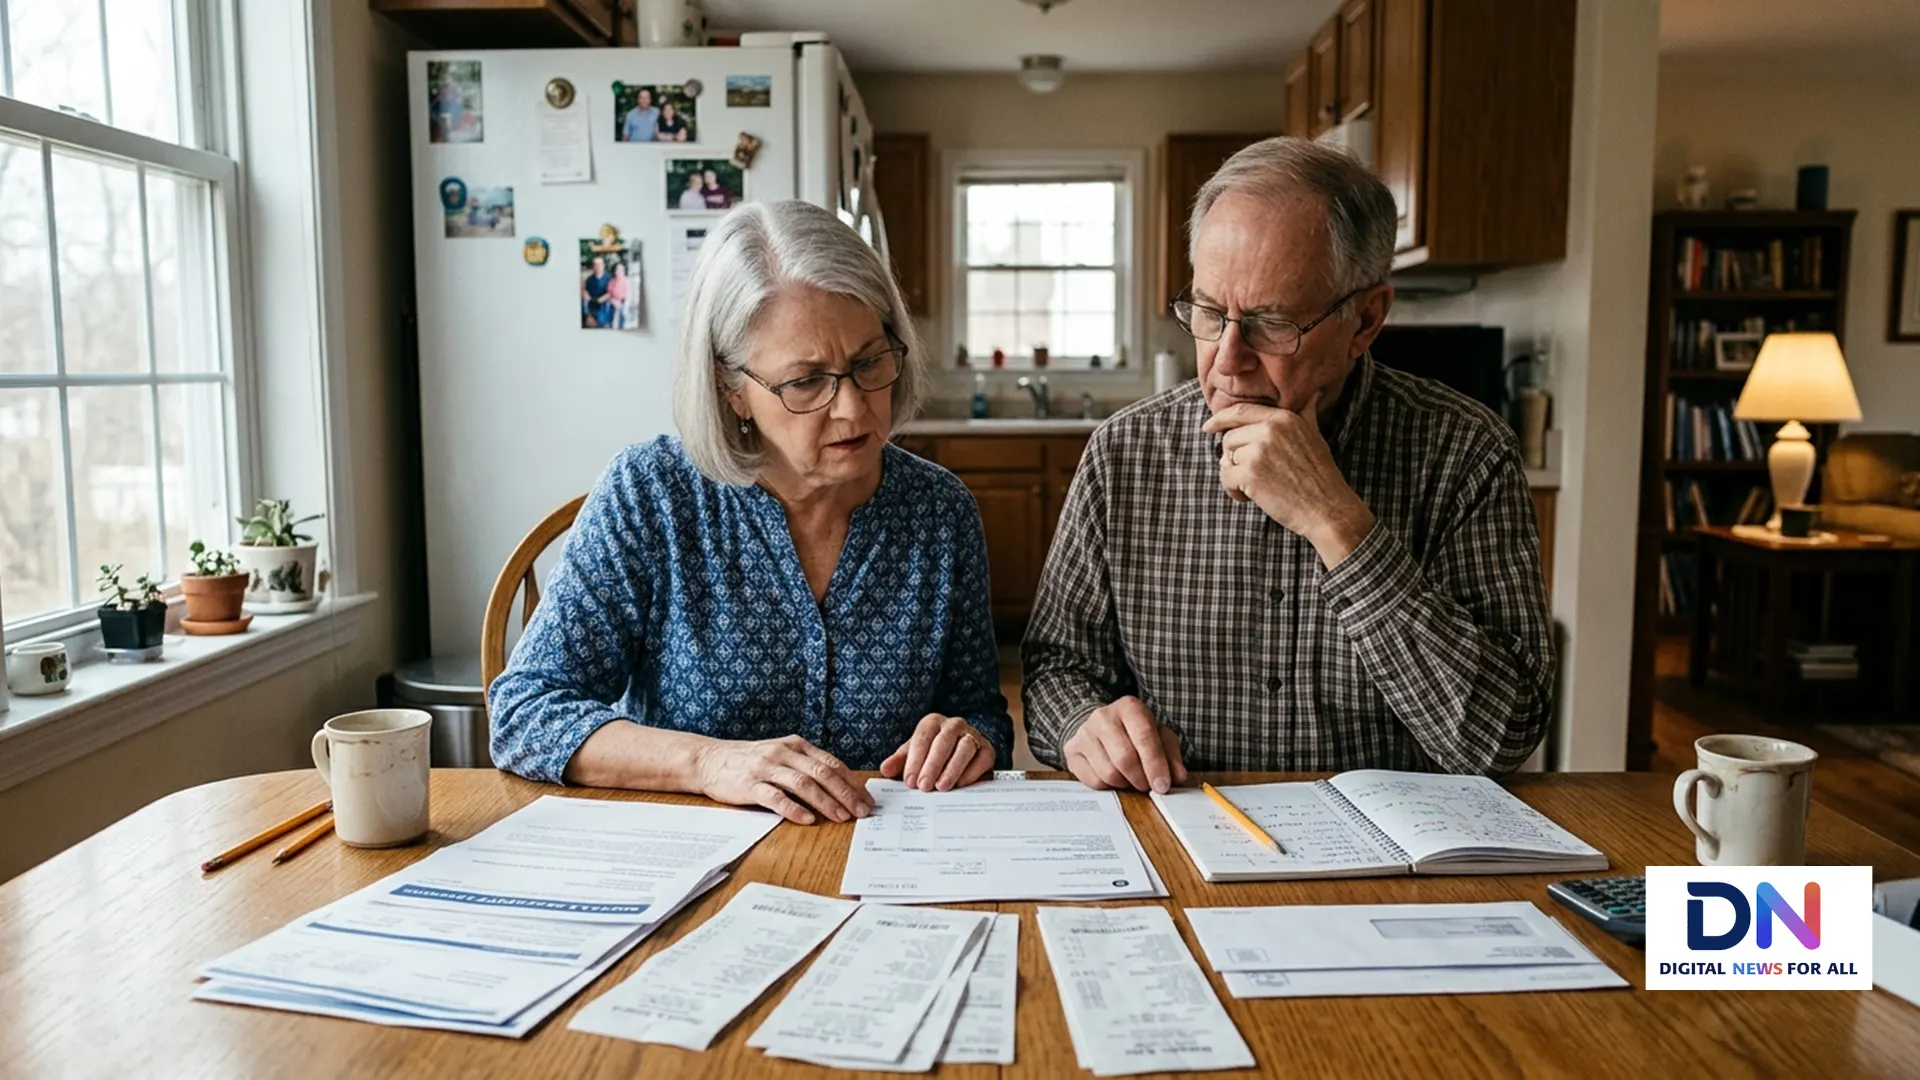
Social Security inflation remains a serious concern for millions of American retirees. Although benefits increase periodically through cost-of-living adjustments (COLAs), those increases do not always match the expenses older Americans face. A 2026 study estimates that Social Security benefits have lost 13.7% of their purchasing power over the past decade.
According to The Senior Citizens League’s 2026 buying-power report, benefits now buy approximately 86 cents’ worth of goods and services for every dollar they could purchase in 2016. This is an estimate from an advocacy organization, rather than an official government measurement.
Why the 13.7% Figure Matters
Inflation gradually reduces what a fixed income can buy. Groceries, rent, utilities, insurance, and healthcare can consume a growing share of a retiree’s monthly budget, even when benefit payments increase.
The Bureau of Labor Statistics tracks consumer price changes through the Consumer Price Index. However, individual retirees may experience inflation differently depending on their housing arrangements, medical needs, and spending patterns.
For older households that spend a large share of their income on essentials, even modest price increases can create difficult financial trade-offs.
The 2026 Social Security COLA
The Social Security Administration confirmed a 2.8% cost-of-living adjustment for 2026, effective with benefits payable in January. The agency estimated that average retirement benefits would rise by approximately $56 per month.
The official 2026 COLA fact sheet explains how the adjustment affects beneficiaries. The formula uses the Consumer Price Index for Urban Wage Earners and Clerical Workers, known as CPI-W, rather than an index specifically designed around older Americans’ spending.
That difference matters because retirees may spend proportionally more on healthcare and housing than the population represented by the COLA formula.
Healthcare Costs Can Reduce the Benefit Increase
A higher gross Social Security payment does not necessarily mean a retiree has more money available to spend. Medicare premiums and other healthcare expenses can absorb part of an annual increase.
The Centers for Medicare & Medicaid Services publishes information about Medicare costs and coverage. Beneficiaries should review applicable premiums and out-of-pocket expenses when assessing their actual monthly income.
The National Council on Aging also provides resources about benefits, financial assistance, and programs that may help eligible older adults manage essential expenses.
Can Social Security Keep Pace With Inflation?
Some advocates support changing the COLA formula to better reflect older Americans’ spending patterns. One proposed alternative is the Consumer Price Index for the Elderly, or CPI-E, which focuses on spending patterns among older households.
The Social Security Administration’s COLA information explains the current calculation method and historical adjustments. Any change to the formula would involve policy decisions and potential financial implications that lawmakers would need to evaluate.
Meanwhile, the Congressional Budget Office provides analysis of Social Security policy and the program’s long-term finances.
What Retirees Can Do Now
Retirees can review their monthly budgets, check eligibility for food and utility assistance, compare Medicare coverage options, and use their official my Social Security account to verify benefit information.
The estimated 13.7% purchasing-power decline highlights a real challenge: annual benefit increases may not fully reflect the expenses individual retirees face. The central issue is not simply whether Social Security checks are rising, but whether those increases allow beneficiaries to maintain their standard of living.
#SocialSecurity #Inflation2026 #RetirementPlanning #SeniorCitizens #CostOfLiving #RetirementIncome #USEconomy